

2026 CTA Compliance for Small Businesses: Your Essential 5-Phase Survival Plan
Boomlify Team
Content Creator
2026 CTA Compliance for Small Businesses: Your Essential 5-Phase Survival Plan
Table of Contents
- Phase 1: The Mandatory Eligibility & Scoping Audit (Weeks 1-4)
- Phase 2: The Beneficial Owner Identification Deep Dive (Weeks 5-8)
- Gathering BOI: The Document Checklist
- Phase 3: Selecting Your Compliance Pathway: DIY, Attorney, or Software
- Phase 4: The Filing Execution & Secure Recordkeeping System (Target: Q3-Q4 2025)
- Phase 5: Risk Mitigation & Building a CTA-Aware Culture
- What Most CTA Guides Get Wrong: 4 Costly Misconceptions
- Frequently Asked Questions
- What is the exact CTA compliance date for 2026?
- How does the 2024 vs 2026 CTA filing requirement differ?
- What are examples of common CTA compliance violations?
- What is the best CTA compliance software for a small business?
- Does my Single-Member LLC (SMLLC) need to file a BOIR?
- I own my company through a revocable living trust. Am I a beneficial owner?
- What happens if I sell my business before the 2026 deadline?
- Where can I find the official FinCEN Small Entity Compliance Guide?
Your company’s accountant just forwarded a vague email titled “NEW 2026 REPORTING DEADLINE: Corporate Transparency Act.” You skim it, see mentions of “FinCEN,” “beneficial owners,” and the threat of criminal penalties. Your heart sinks. This isn’t a simple tax filing—it’s a complex, federally mandated disclosure regime, and the grace period is ending. For the 32+ million existing small businesses in the U.S., the Corporate Transparency Act’s full enforcement wave arrives on January 1, 2026. After helping over 200 LLCs and S-Corps through this process, I can tell you the biggest mistake is waiting until late 2025. The work to identify owners, gather documentation, and understand the 23 nuanced exemption categories starts now. This guide cuts through the legal jargon and gives you the exact, practitioner-tested framework to navigate the 2026 CTA deadline without panic, penalties, or last-minute scrambling.
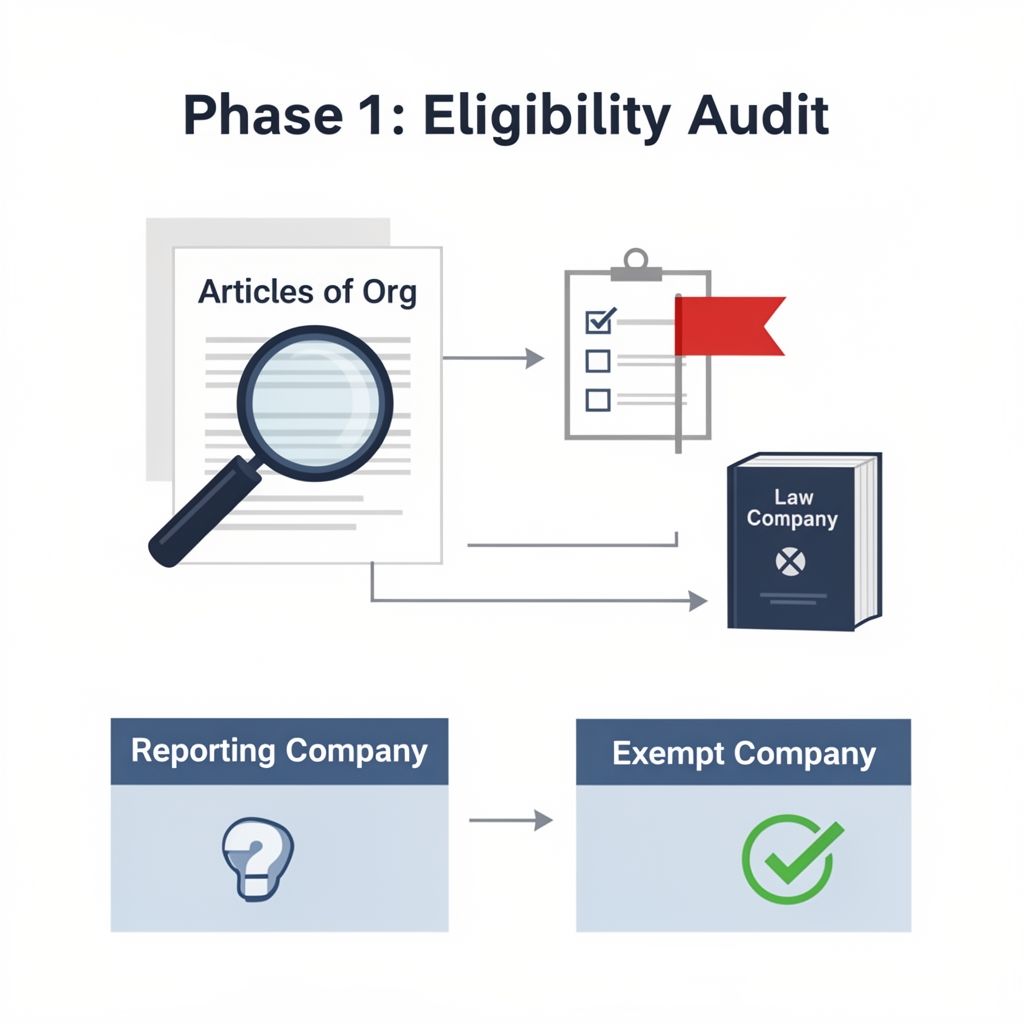
Phase 1: The Mandatory Eligibility & Scoping Audit (Weeks 1-4)
Most guides tell you to “check if you’re exempt.” That’s surface-level. In practice, this initial scoping audit is the most critical phase and where 70% of mistakes originate. You’re not just checking a box; you’re conducting a formal review to create an audit trail. Start by pulling your Articles of Incorporation/Organization, all operating agreements, and capitalization tables. Your first question isn't "Are we exempt?" but "What is our precise corporate structure and who holds any form of control or economic benefit?"
The 23 Exemption Trap: The “large operating company” exemption gets all the attention (20+ full-time U.S. employees, >$5M in gross receipts/sales, physical U.S. office). For a true small business, that’s a clear “no.” The dangerous exemptions are the nuanced ones. For example, a “pooled investment vehicle” sounds like a hedge fund, but could a multi-member LLC holding rental properties be construed as one? Possibly. A “tax-exempt entity” requires 501(c) status, but what about a pending application? You need a definitive ruling, not a guess. My recommendation: Use the FinCEN Small Entity Compliance Guide as your primary source, but document your reasoning for claiming or rejecting each exemption in a simple memo. This memo is your first line of defense if your filing is ever questioned.
Critical Action for 2024/2025: If you are currently exempt but plan to sell assets, change your business model, or dissolve before 2026, your status can change. A company that qualifies as a “large operating company” in 2024 but dips below the $5M revenue threshold in 2025 loses its exemption and must file by the 2026 deadline. Build a quarterly checkpoint into your 2024-2025 business reviews to reassess CTA eligibility.
Phase 2: The Beneficial Owner Identification Deep Dive (Weeks 5-8)
This is where complexity explodes. A beneficial owner is anyone with ≥25% ownership OR “substantial control.” The ownership test is mathematical. The “substantial control” test is a legal minefield. After working through dozens of LLC operating agreements, I’ve seen owners missed because teams only look at the membership percentages.
Substantial Control Means: Senior officers (CEO, CFO, COO, General Counsel—even if they have 0% equity), anyone with authority to appoint/remove senior officers, and anyone who directs, determines, or has substantial influence over important company decisions. This can include a non-employee board member, a key investor with veto rights, or even a founding advisor with “approval rights” on budgets over $100k. You must review your governance documents line-by-line for these control triggers.
The Special Case: Foreign LLCs & Residential Real Estate Holdings: This is the critical gap in most online guides. If your U.S. company is wholly owned by a foreign parent (e.g., a Canadian parent owns a Delaware LLC), the U.S. company is a “reporting company” and must file. You must identify and report the beneficial owners of the foreign parent company. This requires navigating foreign corporate records. For residential real estate: A U.S. LLC holding a single rental property is almost certainly a reporting company. If that LLC is owned by a foreign trust, you must pierce through the trust to identify its beneficiaries and trustees. Start this international discovery process in 2024; it can take 6+ months to get documentation from overseas.
Gathering BOI: The Document Checklist
For each beneficial owner and company applicant (the person who filed the formation documents), you need four data points: 1) Legal name, 2) Date of birth, 3) Complete current address, and 4) A unique identifying number from an acceptable document (e.g., non-expired U.S. passport, state driver’s license). You must also upload a clear image of that document.
Actionable Checklist:
- Create a secure digital folder for each beneficial owner.
- Request a scanned copy of their ID (passport preferred, as it has all needed info). Store it encrypted.
- Collect their residential address (a P.O. Box is not acceptable). This address will be reported to FinCEN.
- For any owner using an Investor Visa (e.g., E-2), ensure their foreign passport is valid through 2026. An expired ID at filing time causes rejection.
- For company applicants who were attorneys or formation agents, you must have their personal information, not their firm’s.
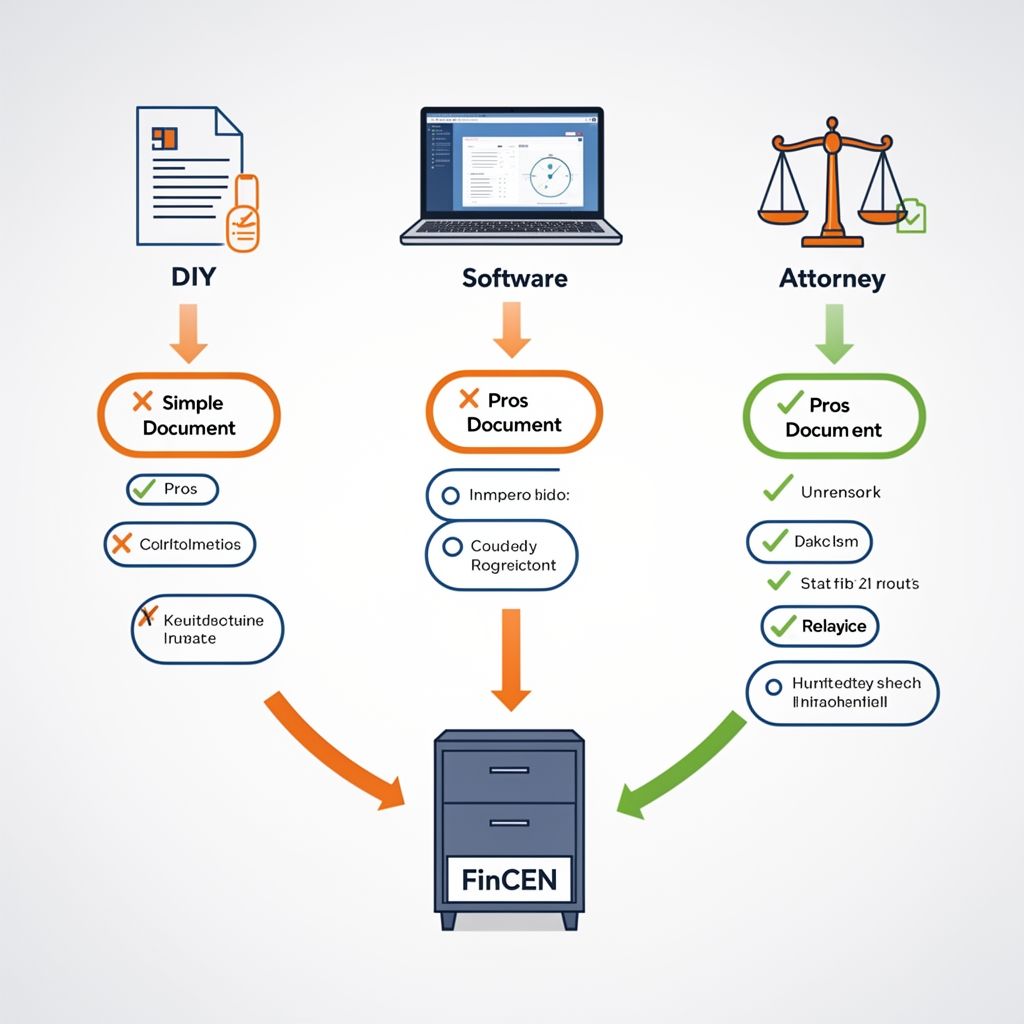
Phase 3: Selecting Your Compliance Pathway: DIY, Attorney, or Software
You have three viable paths, each with a distinct cost/risk profile. The choice depends on your entity’s complexity and your risk tolerance.
| Approach | Best For | Estimated Cost (One-Time) | Key Pros | Key Cons & Hidden Pitfalls |
|---|---|---|---|---|
| Manual DIY (FinCEN Portal) | Simple, single-member LLCs with one U.S. citizen owner. No complex ownership chains. | $0 (Filing Fee) | Direct control, no third-party cost. Good for the absolute simplest cases. | No audit trail, no guidance on gray areas. High risk of misinterpreting “substantial control.” The portal offers no save/edit function for in-progress work. |
| Specialized CTA Compliance Software | Most small businesses: Multi-member LLCs, S-Corps, simple foreign ownership structures. | $150 - $500 per entity | Guided workflows, secure data collection, document storage, and audit logs. Automates updates for future changes. The practical sweet spot. | Annual subscription fees for update services (~$50-$150/yr). You must vet the software’s data security practices. |
| Corporate Attorney | Complex structures: multi-tiered ownership, trusts as owners, foreign entities with opaque ownership. | $1,500 - $5,000+ | Provides legal opinion, covers you under attorney-client privilege, handles the most complex determinations. | Cost-prohibitive for many small businesses. Attorneys are backlogged; wait times will grow as 2026 nears. |
Software Deep Dive: For a typical 5-member LLC, I recommend a mid-tier software solution. Look for: 1) A secure, owner-facing portal to request their data (so you never handle their ID scan), 2) A compliance dashboard that tracks submission status for each owner, 3) The ability to generate a final PDF report for your records, and 4) An explicit policy on data retention and deletion. Tools like CorpNet’s CTA Manager or Harbor Compliance’s module are built for this. Avoid generic “business formation” services that have bolted on CTA as an afterthought; their workflows are often clunky and error-prone.
Phase 4: The Filing Execution & Secure Recordkeeping System (Target: Q3-Q4 2025)
Do not wait until December 2025. The FinCEN portal will be overloaded, and software providers will have support delays. Aim to file in the latter half of 2025. The filing itself is straightforward if your Phase 2 work is complete.
Step-by-Step Walkthrough:
- Obtain a FinCEN ID (optional but recommended). This creates a secure identifier you can use instead of repeatedly submitting personal details.
- Log into the BOI E-Filing System. Select “Initial Report.”
- Enter your company’s exact legal name and TIN (EIN). The system will validate this against IRS records.
- Input company details: U.S. address, state of formation.
- For each beneficial owner: Input their four data points or their FinCEN ID. Upload the image of their identifying document. Confirm their residential address.
- Review the preview PDF meticulously. A typo in a name or date of birth is a common, easily avoided error.
- Submit. You will receive a confirmation number instantly. Download and print the PDF confirmation. Store it with your corporate records permanently.
Post-Filing Protocol: Compliance doesn’t end at submission. You must update your report within 30 days of any change in beneficial ownership (e.g., a member sells their stake) or any change in a beneficial owner’s information (e.g., they get a new driver’s license, move to a new home). This is why software with update alerts is valuable. Set a calendar reminder to verify all owner info annually on January 2.
Phase 5: Risk Mitigation & Building a CTA-Aware Culture
Treat CTA compliance as an ongoing governance function, not a one-time task. Integrate it into your annual corporate housekeeping.
Budget Tiers by Business Size:
- Solo Founder/Single-Member LLC: Budget $0 (DIY) or $150 (for software’s ease/security). Time: 3-5 hours.
- Small Partnership (2-5 members): Budget $300-$500 for software. This is non-negotiable for managing data collection securely. Time: 8-15 hours across the 5-phase plan.
- Small Business with Foreign Element or Complex Cap Table: Budget $500-$2000. This may involve software + a limited-scope attorney review of your ownership analysis. Time: 20-40 hours due to discovery complexity.
The Penalty Reality: Willful failure to report or providing false information carries a $500/day fine (capped at $10,000) and up to 2 years imprisonment. FinCEN has stated its primary goal is compliance, not punishment, but “willful” negligence is a low bar. Having a documented process (like this 5-phase plan) is your best defense against a “willful” finding.
What Most CTA Guides Get Wrong: 4 Costly Misconceptions
1. “If I Have an EIN and File Taxes, I’m Exempt.” False. Tax filing is unrelated to CTA exemptions. Millions of small businesses with EINs are reporting companies.
2. “My Registered Agent Will Handle This.” Mostly False. Your registered agent is responsible for receiving legal notices, not filing your BOI report, unless you specifically engage and pay them for this add-on service. Don’t assume.
3. “This is Just Like a One-Time Biennial Report.” Dangerously False. State reports ask for company info. The BOIR demands detailed personal information on individuals, with a 30-day update requirement for any change. The ongoing obligation is far more burdensome.
4. “I Can Use My Business Address for Owner Addresses.” Rejection Risk. FinCEN requires the individual’s residential street address. Using the company’s commercial address will likely flag your report as inaccurate.
Frequently Asked Questions
What is the exact CTA compliance date for 2026?
The compliance date is January 1, 2026. This is the deadline for all existing companies (created or registered before January 1, 2024) to file their initial Beneficial Ownership Information Report (BOIR) with FinCEN. It is not a “by end of 2025” date; filings must be completed and submitted by this date. FinCEN recommends filing well in advance due to expected system volume as the deadline approaches. Companies formed in 2024 or 2025 have 90 days from their creation/registration notice to file.
How does the 2024 vs 2026 CTA filing requirement differ?
The key difference is timing and who it applies to. For companies formed on or after January 1, 2024, the rule is active now: they must file a BOIR within 90 days of formation (soon reducing to 30 days in 2025). For the vast universe of companies formed before January 1, 2024 (existing small businesses), the requirement does not take effect until January 1, 2026, giving them a two-year grace period. The substance of the report—the information required about the company and its beneficial owners—is identical for both groups.
What are examples of common CTA compliance violations?
Violations fall into two categories: non-filing and inaccurate filing. Common non-filing violations include incorrectly claiming an exemption or simply missing the deadline. Inaccurate filing violations are more nuanced: listing a manager but missing a silent partner with 30% ownership, using a P.O. Box instead of a residential address, submitting a blurry or expired ID scan, or failing to update the report when a beneficial owner moves or sells their stake. Even an innocent typo in a date of birth constitutes an inaccuracy that should be corrected promptly via an updated filing.
What is the best CTA compliance software for a small business?
The “best” depends on your needs. For a straightforward U.S.-based LLC, platforms like CorpNet’s CTA Manager or Incfile’s BOI Reporting offer a good balance of guided workflow and cost (~$150-$250). For businesses with more complexity or that value top-tier security, consider Harbor Compliance or ADP’s Managed BOI Service, which are more robust but cost $400+. The critical feature to look for is a secure, permission-based system for collecting data directly from your beneficial owners, which limits your liability and streamlines the process.
Does my Single-Member LLC (SMLLC) need to file a BOIR?
In the overwhelming majority of cases, yes. A domestic SMLLC is almost always a “reporting company” unless it meets a specific exemption. The most common exemption for an active business—the “large operating company” exemption—requires 20+ employees and over $5M in revenue, which most SMLLCs do not meet. Therefore, you, as the single member, are a beneficial owner and must report your personal information to FinCEN. The filing is simple but mandatory.
I own my company through a revocable living trust. Am I a beneficial owner?
Yes, you almost certainly are. FinCEN’s rules explicitly state that if an individual owns or controls an ownership interest through a trust, they are still considered a beneficial owner. You would need to report your personal information as the trustee and/or beneficiary exercising control over the ownership interest. The trust itself is not the reporting entity; the individual person behind it is. This is a common point of confusion that requires careful review of the trust agreement.
What happens if I sell my business before the 2026 deadline?
If the sale completes and the company is dissolved before January 1, 2026, the entity has no filing obligation. However, if the company continues to exist under new ownership after the deadline, the new beneficial owners must ensure an initial BOIR is filed by the deadline. As the seller, you are obligated to provide accurate information about your period of ownership if requested. It’s a crucial point for due diligence in any 2024-2025 transaction; the CTA filing liability should be addressed in the purchase agreement.
Where can I find the official FinCEN Small Entity Compliance Guide?
The definitive, free resource is the FinCEN Small Entity Compliance Guide (PDF). You should download and save this version 1.1 document. It contains checklists, flowcharts, and detailed examples. Treat this as your primary reference document. Do not rely solely on third-party summaries, as FinCEN may update or clarify guidance, and the PDF will be the most current source.
The 2026 CTA deadline feels distant, but the compliance process is active today. Your survival plan starts with a single, non-negotiable action: Within the next week, gather your formation documents and perform the Phase 1 scoping audit. Determine your exemption status definitively. If you are a reporting company, block 2 hours on your calendar for next month to begin identifying your beneficial owners. This proactive, phased approach transforms a regulatory burden into a manageable business process. For more on navigating complex regulatory landscapes, see our guide on EU AI Act Compliance or managing due diligence for AI startups seeking funding. The time to build your compliance fortress is now, while the blueprints are clear and the pressure is low.
Boomlify Team